Agri Infrastructure Development
Cess and EOUs
[Circular No. 07/2021-Customs
dated 22 February 2021]
Subject: Clarification regarding payment
of Agriculture Infrastructure and Development Cess (AIDC) by EOU
under various situations and amendment
to Circular no. 35/2016-Customs dated 29.07.2020.
Finance Bill, 2021 (15 of 2021) dated 01.02.2021, vide clause 115 has imposed a duty
of customs, to be called Agriculture Infrastructure
and Development Cess (AIDC),
on
the import of goods specified in the First Schedule to the Customs Tariff Act, 1975 at the rate not exceeding the rate of customs duty as specified in the said Schedule, for the purposes of financing the agriculture infrastructure and other
development expenditure.
The
said provision of clause 115 of
the
Bill has been given immediate effect under
the
Provisional Collection of
Taxes
Act,
1931.
1.1 In exercise of the powers conferred by sub-section (1) of section 25 of the
Customs Act, 1962 (52 of 1962) read with clause 115 of the said bill, Government of India vide Notification No. 11/2021- Customs dated 1st
February, 2021 vide
Sr.
no. 19 read with serial no. 7 of the Annexure to the said notification has fully exempted goods imported
by EOUs/EHTP
units/STP
units (collectively
called EOUs) from the AIDC as the goods imported by these units enjoy benefit of
exemption from basic customs duty under notification no. 52/2003-Cus dated 31.03.2003.
1.2 In case of EOU selling finished goods in DTA, BCD exempted on import of inputs used in such finished
goods
is to be paid vide Notification No. 59/2017- Customs dated 30.06.2017 [amending by Notification No. 52/2003-Customs dated 31.03.2003]. On payment of such BCD by EOU at the time of clearance of
finished goods it is treated as if no exemption of BCD was allowed to the EOU under Notification No. 52/2003-Customs dated 31.03.2003. Once it is deemed that no exemption of BCD on inputs is allowed which were imported under
exemption Notification No. 52/2003-Customs dated
31.03.2003, AIDC
exemption under
Notification
no.
11/2021-Customs dated 01.2.2021
also gets denied on
such inputs and same
is also
required to
be paid by EOU.
1.3 In addition to clearance of
goods in DTA
there are many situations like
clearance of inputs; capital goods; packing material suitable for repeated
use such
empty cones, bobbins, containers; left over textile fabric or textile material etc. or
exit from EOU scheme. In such cases duty/tax of which exemption under Notification No. 52/2003-Customs dated
31.03.2003 was
availed at the time of import is required to be paid at the time of
clearance. In case of
clearance of capital
goods, applicable depreciation is allowed for denial of exemption. Unutilized left over textile fabric
or
textile material
is allowed
to be cleared into
DTA
on payment
of duty
leviable
at the time of import but for the exemption on transaction value as if the goods have been manufactured in that unit. Exemption of duty/tax
on goods
imported under
Notification No.
52/2003-Customs dated 31.03.2003 is also denied
on
account of breach of various conditions of EOU scheme. Once EOU is required
to pay back BCD for which exemption was claimed and allowed under Notification No. 52/2003-Customs
dated 31.03.2003 at the time of import then exemption of AIDC, if availed, in all such situations shall also be denied. Thus, EOU shall be
required to pay AIDC in the manner of payment of BCD
against
the
goods imported
under exemption Notification No. 52/2003-Customs
dated 31.03.2003
under various situations.
2.
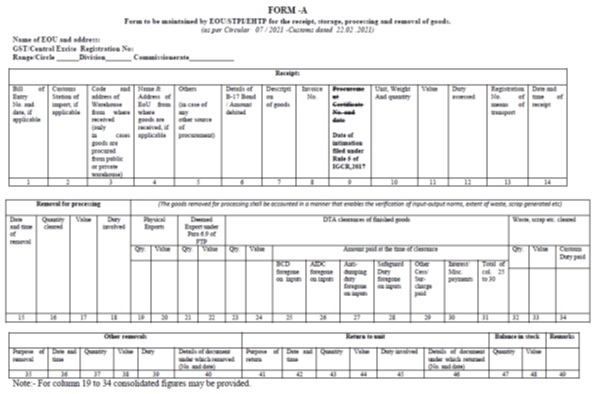
EOU/STP/EHTP are required to maintain and also
submit digital copy of
Form
– A
to Circular no. 35/2016-Customs dated 29.07.2016,
by 10th of month to
proper officer, which captures
the
summary of receipt, removal, returns and balance of
imported goods under
Notification
No.
52/2003-Customs
dated
31.03.2003. Copy of
Quarterly
Performance Report
and Annual
Performance Reports [QPR/APR] are also required to be submitted to jurisdictional AC/DC of Customs as mandated by DGFT Public Notice no. 36/2015-2020 dated 04.09.218. Though
QPR/APR
contain
details
of various activities
including
revenue contribution by EOUs but these are reflected in consolidated manner and these
reports may
be a monitoring tool
for
departmental officers
with limitations. However, for
effective and monthly monitoring of
exemption of duty/taxes availed
under Notification No.
52/2003-Customs dated 31.03.2003, the said Form
‘A’ is
amended and revised Form ‘A’
is annexed herewith. Circular no.
35/2016-Customs
dated 29.07.2016 may be treated as amended to above
extent.
3.
Difficulties, if any, may be brought to the
notice
of
Board.
Encl: -
Revised Form ‘A’
F.No. DGEP/SEZ/09/2017 (Part
III)