Pradhan Mantri
Jan-Dhan Yojana (PMJDY) -
National Mission for Financial Inclusion, Completes Seven years of Successful
Implementation
·
More than 43.04 crore
beneficiaries banked under PMJDY since inception, amounting to Rs. 146,231 crore
·
“The journey of PMJDY led
interventions undertaken over a short span of 7 years has in effect, produced
both transformational as well as directional change thereby making the emerging
FI ecosystem capable of delivering financial services to the last person of the
society-the poorest of the poor”– Minister of Finance & Corporate Affairs,
Smt. Nirmala Sitharaman
·
“Financial Inclusion is among
top-most priorities of the Government as it is an enabler for inclusive
growth.”- MoS Finance, Dr. Bhagwat Karad
·
PMJDY Accounts have grown
three-fold from 14.72 Crore in Mar’15 to 43.04 Crore as on 18-08-2021
·
55% Jan-Dhan
account holders are women and 67% Jan Dhan accounts
are in rural and semi-urban areas
·
Out of total 43.04 crore PMJDY
accounts, 36.86 crore (86%) are operative
·
Total RuPay
cards issued to PMJDY accountholders: 31.23 Crore
·
Under PM Garib
Kalyan Yojana, a total of Rs. 30,945 crore have been credited in accounts of women
PMJDY account holders during Covid lockdown
·
About 5.1 crore PMJDY
accountholders receive direct benefit transfer (DBT) from the Government under
various schemes
Ministry of Finance is committed to provide
financial inclusiveness and support to the marginalized and hitherto
socio-economically neglected classes. Financial Inclusion is a national priority
of the Government as it is an enabler for inclusive growth. It is important as
it provides an avenue to the poor for bringing their savings into the formal
financial system, an avenue to remit money to their families in villages
besides taking them out of the clutches of the usurious money lenders. A key
initiative towards this commitment is the Pradhan Mantri
Jan Dhan Yojna (PMJDY),
which is one of the biggest financial inclusion initiatives in the world.
PMJDY was announced by Prime Minister, Narendra
Modi in his Independence Day address on 15th August 2014. While launching the programme on 28th August, the Prime Minister had described
the occasion as a festival to celebrate the liberation of the poor from a
vicious cycle.
On the 7th Anniversary of PMJDY,
Finance Minister Smt. Nirmala Sitharaman reiterated
the importance of this Scheme “The journey of PMJDY led interventions
undertaken over a short span of 7 years has in effect, produced both
transformational as well as directional change thereby making the emerging FI
ecosystem capable of delivering financial services to the last person of the
society-the poorest of the poor. The underlying pillars of PMJDY, namely,
Banking the Unbanked, Securing the Unsecured and Funding the Unfunded has made
it possible to adopt multi-stakeholders’ collaborative approach while
leveraging technology for serving the unserved and underserved areas as well.”
she said
Minister of State for Finance, Dr. Bhagwat Karad also expressed his thoughts for PMJDY on this occasion.
He said “Pradhan Mantri Jan Dhan
Yojana (PMJDY) has been one of the most far reaching
initiatives towards Financial Inclusion not only in India but in the world.
Financial Inclusion is among top-most priorities of the Government as it is an
enabler for inclusive growth. It provides an avenue to the poor for bringing
their savings into the formal financial system, an avenue to remit money to
their families besides taking them out of the clutches of the usurious money
lenders.”
As we complete 7 years of successful
implementation of this Scheme, we take a look at the major aspects and
achievements of this Scheme so far.
Background
Pradhan Mantri Jan-Dhan Yojana (PMJDY) is National
Mission for Financial Inclusion to ensure access to financial services, namely,
Banking/ Savings & Deposit Accounts, Remittance, Credit, Insurance, Pension
in an affordable manner.
1.
Objectives:
o Ensure access of financial products & services at an
affordable cost
o Use of technology to lower cost & widen reach
2.
Basic tenets of the scheme
o Banking the unbanked - Opening of basic savings
bank deposit (BSBD) account with minimal paperwork, relaxed KYC, e-KYC, account
opening in camp mode, zero balance & zero charges
o Securing the unsecured - Issuance of Indigenous
Debit cards for cash withdrawals & payments at merchant locations, with
free accident insurance coverage of Rs. 2 lakh
o Funding the unfunded - Other financial products
like micro-insurance, overdraft for consumption, micro-pension &
micro-credit
3.
Initial Features
The
scheme was launched based upon the following 6 pillars:
·
Universal access to banking services – Branch and BC
·
Basic savings bank accounts with overdraft facility of Rs. 10,000/- to every eligible adult
·
Financial Literacy Program– Promoting savings, use of ATMs,
getting ready for credit, availing insurance and pensions, using basic mobile
phones for banking
·
Creation of Credit Guarantee Fund – To provide banks some
guarantee against defaults
·
Insurance – Accident cover up to Rs.
1,00,000 and life cover of Rs. 30,000 on account opened between 15 Aug 2014 to 31
January 2015
·
Pension scheme for Unorganized sector
4. Important
approach adopted in PMJDY based on past experience:
o
Accounts opened are online accounts in core
banking system of banks, in place of earlier method of offline accounts opening
with technology lock-in with the vendor
o
Inter-operability through RuPay
debit card or Aadhaar enabled Payment System (AePS)
o
Fixed-point Business Correspondents
o
Simplified KYC / e-KYC in place of cumbersome KYC
formalities
5. Extension
of PMJDY with New features – The
Government decided to extend the comprehensive PMJDY program beyond 28.8.2018
with some modifications
·
Focus shift from ‘Every Household’ to Every
Unbanked Adult’
·
RuPay Card
Insurance - Free accidental insurance cover on RuPay
cards increased from Rs. 1 lakh to Rs. 2 lakh for PMJDY accounts opened after 28.8.2018.
·
Enhancement in overdraft facilities -
·
OD limit doubled from Rs 5,000/- to Rs 10,000/-; OD upto Rs 2,000/- (without conditions).
·
Increase in upper age limit for OD from 60 to 65 years
6. Impact of PMJDY
PMJDY
has been the foundation stone for people-centric economic initiatives. Whether
it is direct benefit transfers, COVID-19 financial assistance, PM-KISAN,
increased wages under MGNREGA, life and health insurance cover, the first step
of all these initiatives is to provide every adult with a bank account, which
PMJDY has nearly completed.
One in 2 accounts opened between Mar’14 to Mar’20 was a PMJDY
account. Within 10 days of nationwide lockdown more than about 20 crore women
PMJDY accounts were credited with ex-gratia.
Jandhan provides an avenue to the poor for bringing
their savings into the formal financial system, an avenue to remit money to
their families in villages besides taking them out of the clutches of the
usurious money lenders. PMJDY has brought the unbanked into the banking system,
expanded the financial architecture of India and brought financial inclusion to
almost every adult.
In
today's COVID-19 times, we have witnessed the remarkable swiftness and
seamlessness with which Direct Benefit Transfer (DBTs) have empowered and
provided financial security to the vulnerable sections of society. An important
aspect is that DBTs via PM Jan Dhan accounts have
ensured every rupee reaches its intended beneficiary and preventing systemic
leakage.
7. Achievements under PMJDY- As on 18th August’21:
a. PMJDY
Accounts

·
As on 18th August ’21 number of total PMJDY Accounts:
43.04 Crore; 55.47% (23.87 crore) Jan-Dhan account
holders are women and 66.69% (28.70 crore) Jan Dhan
accounts are in rural and semi-urban areas
·
During first year of scheme 17.90 crore PMJDY accounts were
opened
·
Continuous increase in no of accounts under PMJDY
·
PMJDY Accounts have grown three-fold from 14.72 Crore in Mar’15
to 43.04 Crore as on 18-08-2021. Undoubtedly a remarkable journey for the
Financial Inclusion Program.
b. Operative
PMJDY Accounts –

·
As per extant RBI guidelines, a PMJDY account is treated as
inoperative if there are no customer induced transactions in the account for
over a period of two years
·
In August’21, out of total 43.04 crore PMJDY accounts, 36.86
crore (85.6%) are operative
·
Continuous increase in % of operative accounts is an indication
that more an more of these accounts are being used by
customers on a regular basis
·
Only 8.2% PMJDY accounts are zero balance accounts
c.
Deposits under PMJDY accounts -

·
Total deposit balances under PMJDY Accounts stand at Rs. 1,46,230 crore
·
Deposits have increased about 6.38 times with increase in
accounts 2.4 times (Aug’21 / Aug’15)
d. Average
Deposit per PMJDY account -

·
Average deposit per account is Rs.
3,398
·
Avg. Deposit per account has increased over 2.7 times over
Aug’15
·
Increase in average deposit is another indication of increased
usage of accounts and inculcation of saving habit among account holders
e. Rupay Card issued to PMJDY
account holders
·
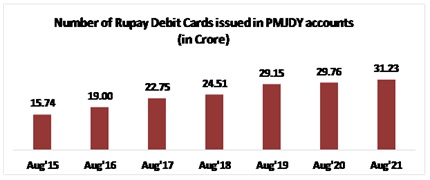
Total RuPay cards issued to PMJDY
accountholders: 31.23 Crore
·
Number of RuPay cards & their
usage has increased over time
8. Jan Dhan Darshak App
A mobile application, was launched to provide
a citizen centric platform for locating banking touch points such as bank
branches, ATMs, Bank Mitras, Post Offices, etc. in
the country. Over 8 lakh banking touchpoints have been mapped on the GIS App.
The facilities under Jan Dhan Darshak
App could be availed as per the need and convenience of common people. The web
version of this application could be accessed at the link http://findmybank.gov.in.
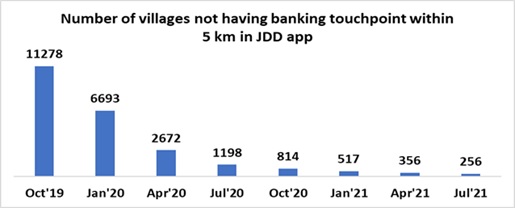
This app is also being used for identifying
villages which are not served by banking touchpoints within 5 km. these
identified villages are then allocated to various banks by concerned SLBCs for
opening of banking outlets. The efforts have resulted in significant decrease
in number of such villages.
9. Pradhan
Mantri Garib Kalyan Package (PMGKP) for PMJDY women beneficieries
As per announcement made by the Hon’ble
Finance Minister on 26.3.2020, under PM Garib Kalyan Yojana, an amount of Rs. 500/- per month for three months (April’20 to June’20),
was credited to the accounts of women account holders under Pradhan Mantri Jan Dhan Yojana (PMJDY). A total of Rs.
30,945 crore have been credited in accounts of women PMJDY account holders
during Covid lockdown
10. Towards
ensuring smooth DBT transactions:
As informed by banks, about 5 crore PMJDY
accountholders receive direct benefit transfer (DBT) from the Government under
various schemes.To ensure that the eligible
beneficiaries receive their DBT in time, the Department takes active role in
identification of avoidable reasons for DBT failures in consultation with DBT
Mission, NPCI, banks and various other Ministries. With close monitoring in
this regard through regular VCs with banks and NPCI, the share of DBT failures
due to avoidable reasons as a percentage of total DBT failures has decreased from
13.5% (FY 19-20) to 5.7% (FY 20-21).
11. The
road ahead
i.
Endeavour to ensure
coverage of PMJDY account holders under micro insurance schemes. Eligible PMJDY
accountholders will be sought to be covered under PMJJBY and PMSBY. Banks have
already been communicated about the same.
ii.
Promotion of digital
payments including RuPay debit card usage amongst
PMJDY accountholders through creation of acceptance infrastructure across India
iii.
Improving access of PMJDY
account holders to Micro-credit and micro investment such as flexi-recurring
deposit etc.